All Categories
Featured


Analyzing Bankruptcy Attorney Costs in 2026
That's you. If you are overwhelmed with financial obligation, make certain you think about all financial obligation relief choices and determine what's finest for you.
As we go into 2026, the insolvency landscape is prepared for to shift in methods that will substantially impact creditors this year. After years of post-pandemic uncertainty, filings are climbing progressively, and economic pressures continue to impact customer behavior. During a current Ask a Pro webinar, our specialists, Investor Milos Gvozdenovic and Lawyer Garry Masterson, weighed in on what lending institutions ought to expect in the coming year.
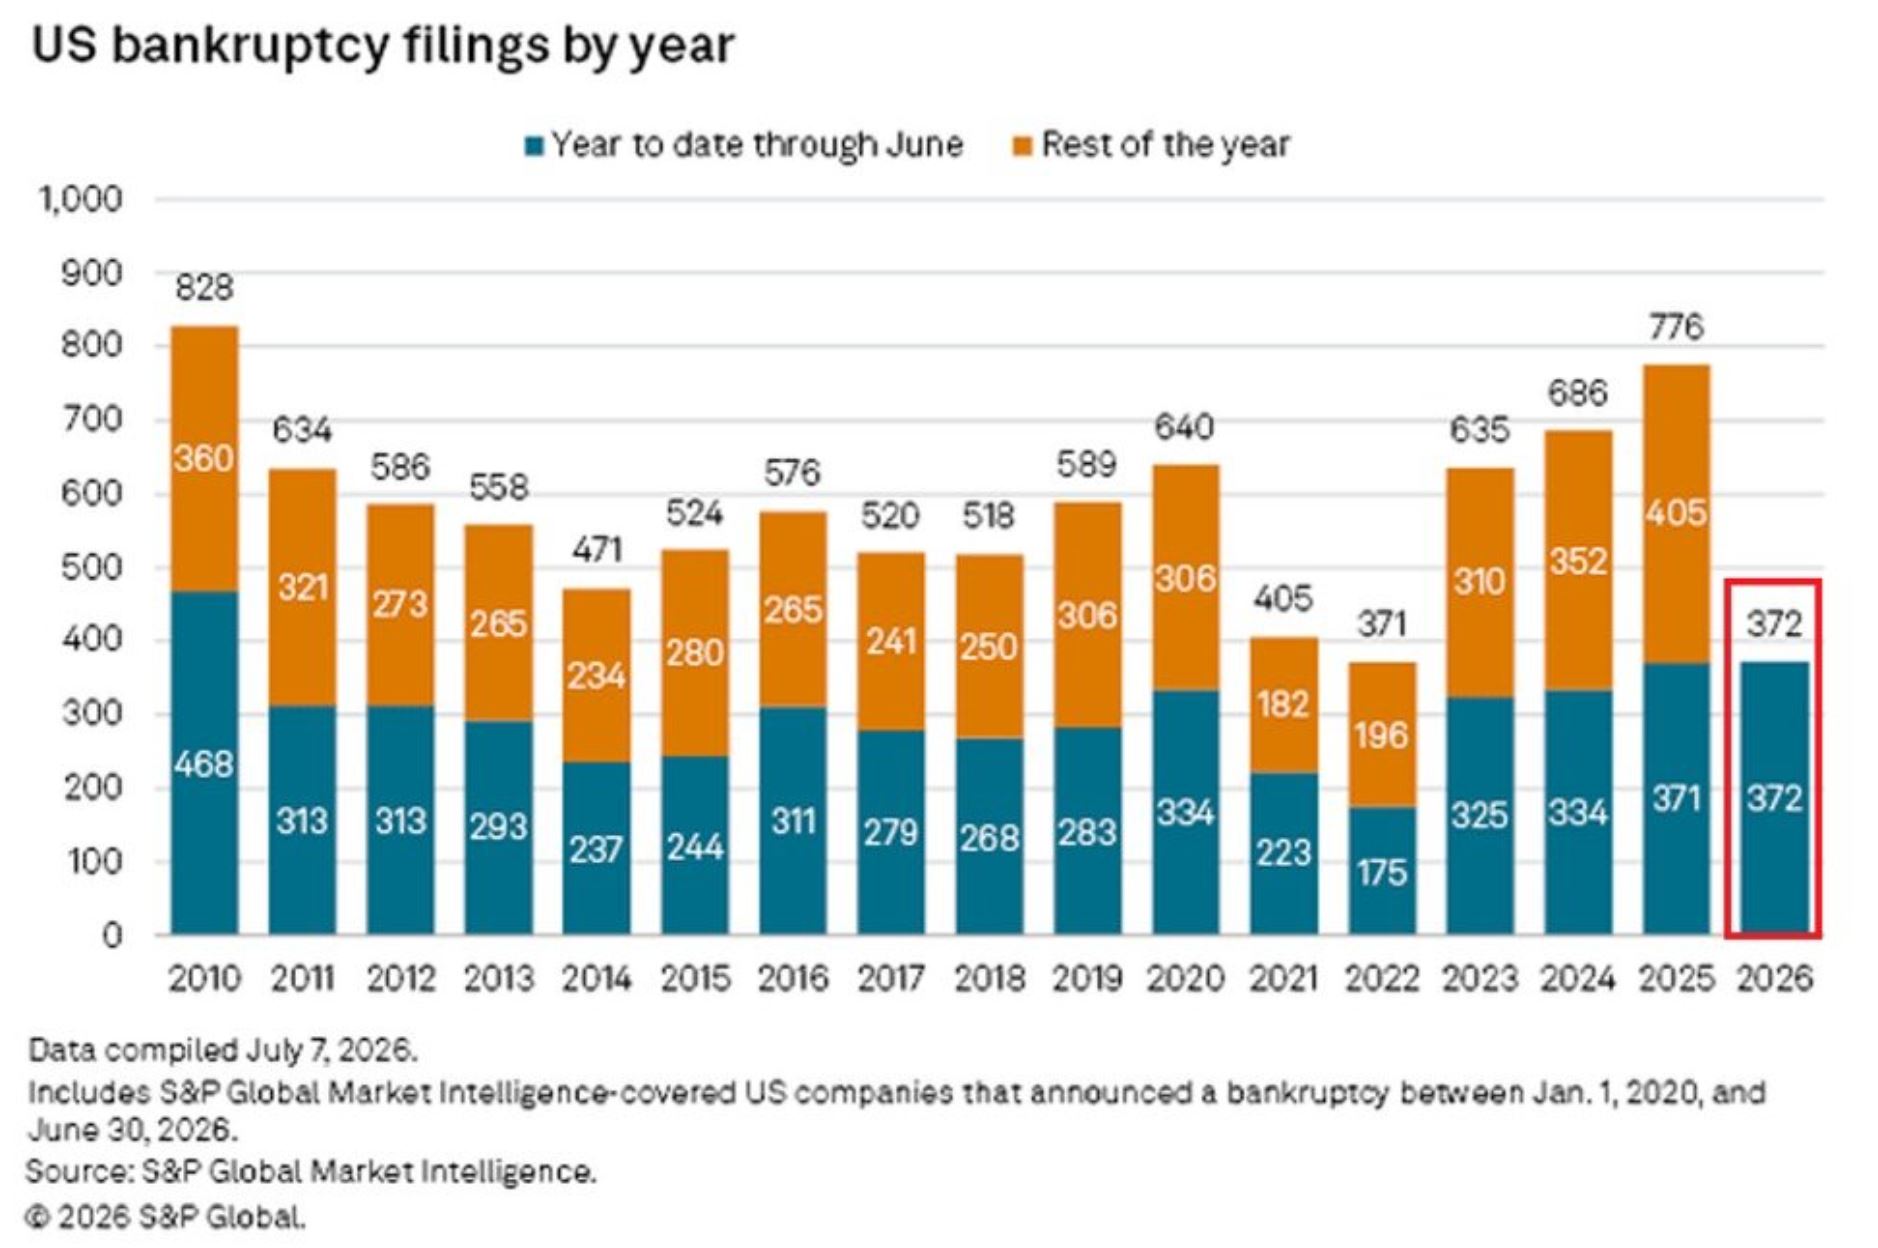
Qualification Standards to File for Bankruptcy in 2026The most prominent trend for 2026 is a continual increase in personal bankruptcy filings. While filings have actually not reached pre-COVID levels, month-over-month growth suggests we're on track to exceed them soon.
A Guide to 2026 Bankruptcy Costs
While chapter 13 filings continue to increase, chapter 7 filings, the most typical type of customer insolvency, are anticipated to dominate court dockets. This trend is driven by consumers' lack of disposable earnings and mounting financial stress.
Indicators such as customers utilizing "purchase now, pay later" for groceries and surrendering just recently acquired lorries show financial stress. As a financial institution, you might see more foreclosures and automobile surrenders in the coming months and year. You should also prepare for increased delinquency rates on car loans and home mortgages. It's also crucial to carefully keep track of credit portfolios as financial obligation levels remain high.
We predict that the real effect will hit in 2027, when these foreclosures transfer to conclusion and trigger insolvency filings. Rising residential or commercial property taxes and homeowners' insurance coverage expenses are already pressing novice lawbreakers into financial distress. How can financial institutions stay one action ahead of mortgage-related personal bankruptcy filings? Your group needs to finish an extensive evaluation of foreclosure processes, protocols and timelines.
Navigating Bankruptcy Fees in 2026Many impending defaults might develop from previously strong credit sectors. Over the last few years, credit reporting in insolvency cases has actually ended up being one of the most contentious topics. This year will be no various. But it is very important that creditors stand company. If a debtor does not reaffirm a loan, you need to not continue reporting the account as active.
Here are a couple of more finest practices to follow: Stop reporting released financial obligations as active accounts. Resume typical reporting just after a reaffirmation arrangement is signed and filed.
Estimating Bankruptcy Attorney Costs
These cases typically create procedural problems for creditors. They can even miss out on essential court hearings. Once again, these problems include intricacy to insolvency cases.
Some recent college graduates might manage commitments and resort to insolvency to handle overall financial obligation. The failure to perfect a lien within 30 days of loan origination can result in a financial institution being dealt with as unsecured in personal bankruptcy.
Our team's recommendations include: Audit lien excellence processes frequently. Preserve documents and proof of prompt filing. Consider protective measures such as UCC filings when delays occur. The bankruptcy landscape in 2026 will continue to be formed by financial uncertainty, regulative scrutiny and progressing consumer behavior. The more prepared you are, the much easier it is to navigate these challenges.
By preparing for the patterns mentioned above, you can alleviate direct exposure and keep functional durability in the year ahead. This blog site is not a solicitation for service, and it is not meant to make up legal advice on particular matters, produce an attorney-client relationship or be legally binding in any way.

Latest Posts
Evaluating Chapter 7 and Chapter 13
Hiring the Best Bankruptcy Counsel for 2026 Claims
Rebuilding Personal Credit After Bankruptcy