All Categories
Featured


Breakdown of Legal Fees
That's you. If you are overwhelmed with debt, be sure you consider all debt relief alternatives and identify what's finest for you.
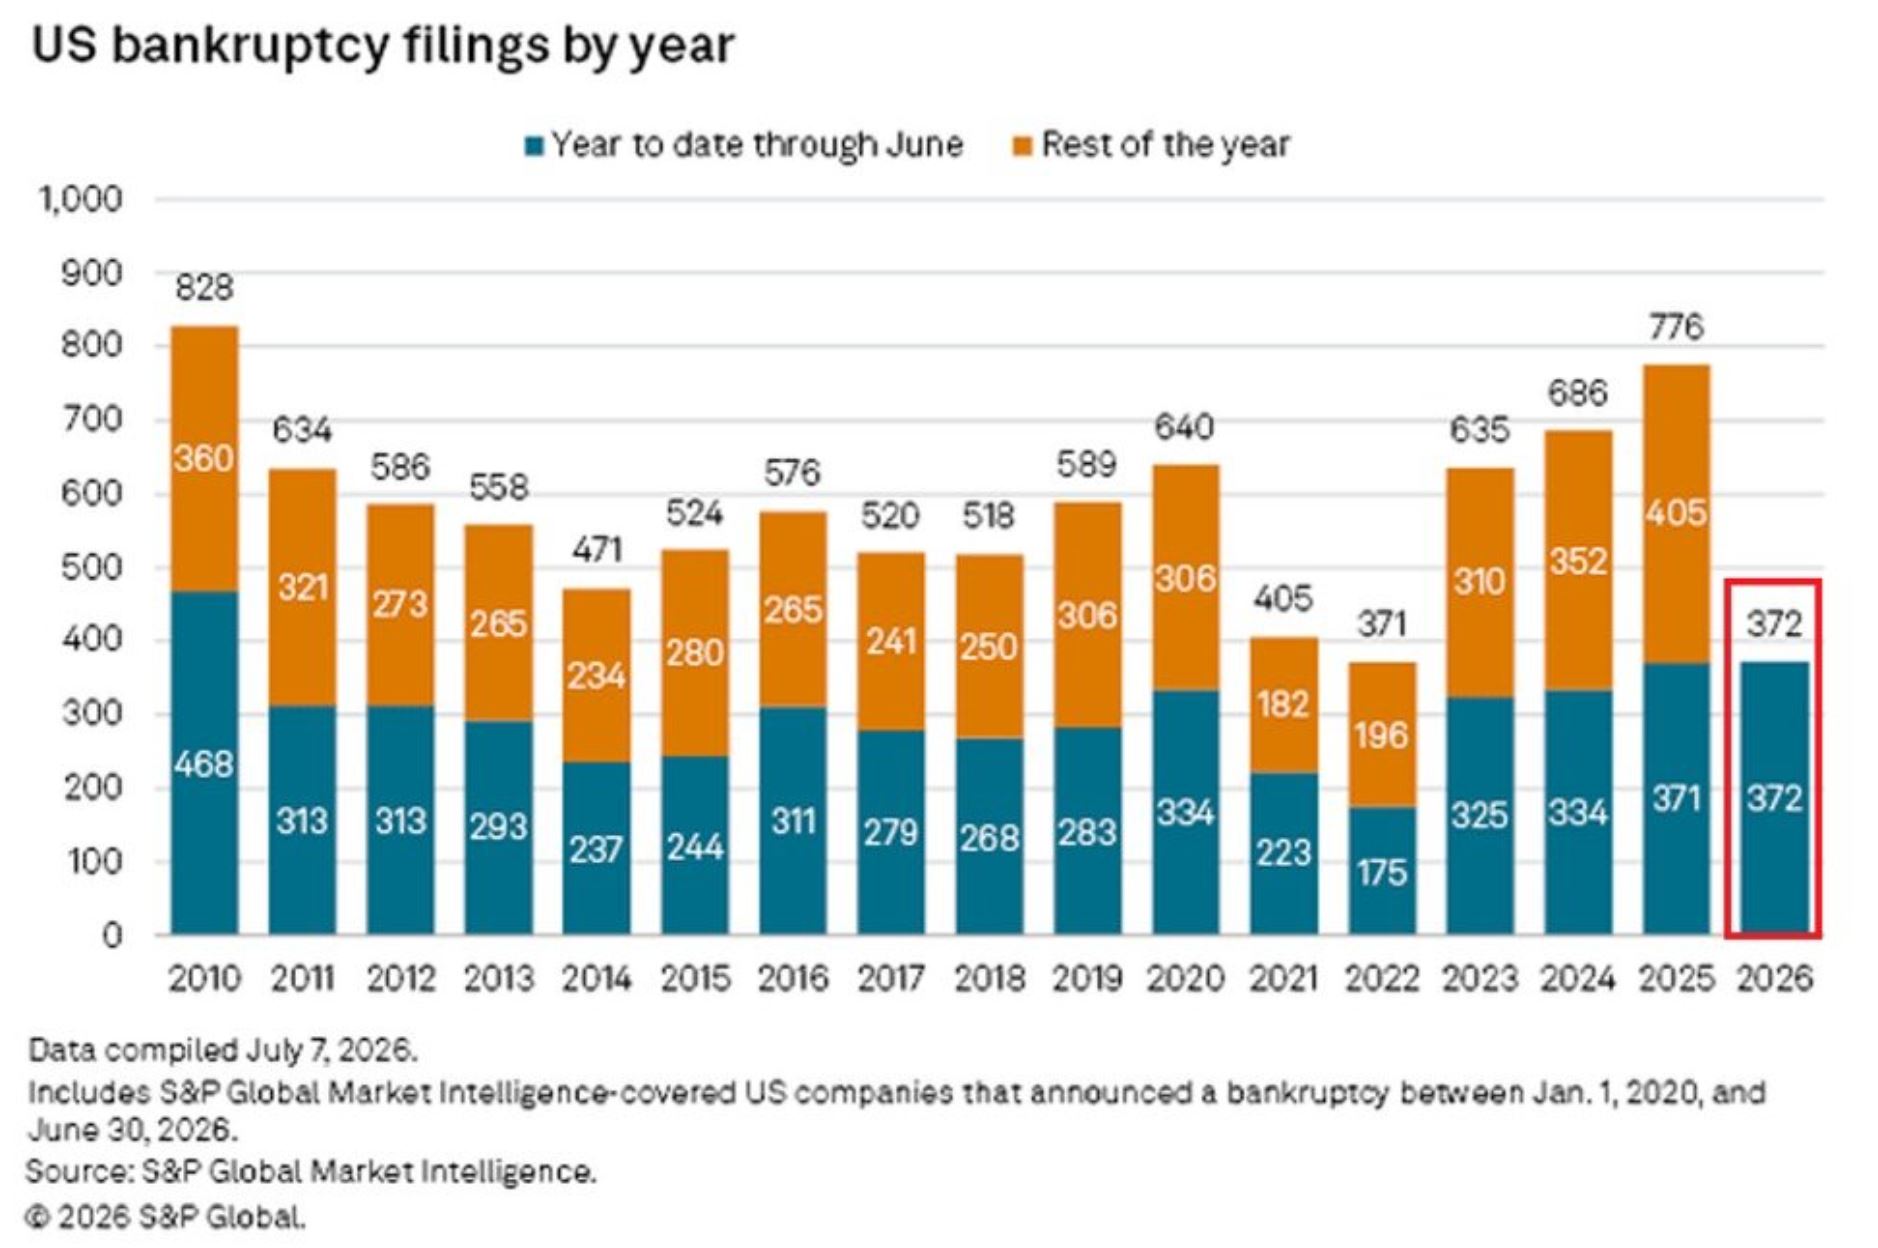
As we enter 2026, the insolvency landscape is anticipated to move in methods that will considerably affect creditors this year. After years of post-pandemic uncertainty, filings are climbing progressively, and financial pressures continue to impact customer behavior.
Calculating Legal Lawyer Costs for 2026For a deeper dive into all the commentary and concerns addressed, we suggest seeing the complete webinar. The most prominent pattern for 2026 is a continual boost in bankruptcy filings. While filings have actually not reached pre-COVID levels, month-over-month growth suggests we're on track to surpass them soon. As of September 30, 2025, insolvency filings increased by 10.6 percent compared to the previous fiscal year.
Essential Legal Support
While chapter 13 filings continue to heighten, chapter 7 filings, the most common kind of customer bankruptcy, are expected to dominate court dockets. This trend is driven by consumers' absence of disposable income and mounting financial stress. Other key drivers consist of: Consistent inflation and raised rate of interest Record-high credit card financial obligation and depleted cost savings Resumption of federal student loan payments Despite recent rate cuts by the Federal Reserve, rate of interest stay high, and loaning expenses continue to climb up.
You should likewise prepare for increased delinquency rates on automobile loans and mortgages. It's also important to carefully keep track of credit portfolios as financial obligation levels stay high.
We predict that the real effect will hit in 2027, when these foreclosures move to completion and trigger insolvency filings. How can lenders remain one step ahead of mortgage-related insolvency filings?
Lots of upcoming defaults may develop from formerly strong credit sections. Recently, credit reporting in bankruptcy cases has actually ended up being one of the most controversial topics. This year will be no different. However it is necessary that lenders stand company. If a debtor does not declare a loan, you must not continue reporting the account as active.
Here are a couple of more finest practices to follow: Stop reporting released debts as active accounts. Resume normal reporting only after a reaffirmation agreement is signed and submitted. For Chapter 13 cases, follow the plan terms thoroughly and speak with compliance teams on reporting obligations. As customers end up being more credit savvy, errors in reporting can lead to disagreements and prospective lawsuits.
Evaluating the Impact of Bankruptcy
Another trend to view is the increase in pro se filingscases filed without lawyer representation. These cases often create procedural complications for financial institutions. Some debtors might stop working to accurately divulge their properties, earnings and expenditures. They can even miss out on crucial court hearings. Once again, these concerns add complexity to personal bankruptcy cases.
Some recent college grads may manage responsibilities and resort to bankruptcy to handle total debt. The takeaway: Financial institutions need to get ready for more complex case management and think about proactive outreach to borrowers dealing with significant monetary strain. Lastly, lien perfection stays a significant compliance threat. The failure to best a lien within 30 days of loan origination can result in a lender being dealt with as unsecured in insolvency.
Our team's recommendations include: Audit lien perfection processes frequently. Keep paperwork and proof of timely filing. Think about protective procedures such as UCC filings when hold-ups take place. The insolvency landscape in 2026 will continue to be formed by financial uncertainty, regulative examination and progressing customer habits. The more ready you are, the simpler it is to browse these challenges.
By anticipating the trends discussed above, you can reduce direct exposure and preserve functional strength in the year ahead. This blog site is not a solicitation for service, and it is not planned to constitute legal suggestions on specific matters, produce an attorney-client relationship or be lawfully binding in any way.

Latest Posts
Evaluating Chapter 7 and Chapter 13
Hiring the Best Bankruptcy Counsel for 2026 Claims
Rebuilding Personal Credit After Bankruptcy