All Categories
Featured

Expert Tips for Filing in 2026
That's you. If you are overwhelmed with debt, make sure you think about all financial obligation relief choices and determine what's finest for you.
As we go into 2026, the bankruptcy landscape is expected to move in manner ins which will significantly impact creditors this year. After years of post-pandemic unpredictability, filings are climbing up gradually, and economic pressures continue to affect consumer habits. During a current Ask a Pro webinar, our professionals, Shareholder Milos Gvozdenovic and Attorney Garry Masterson, weighed in on what lenders must anticipate in the coming year.
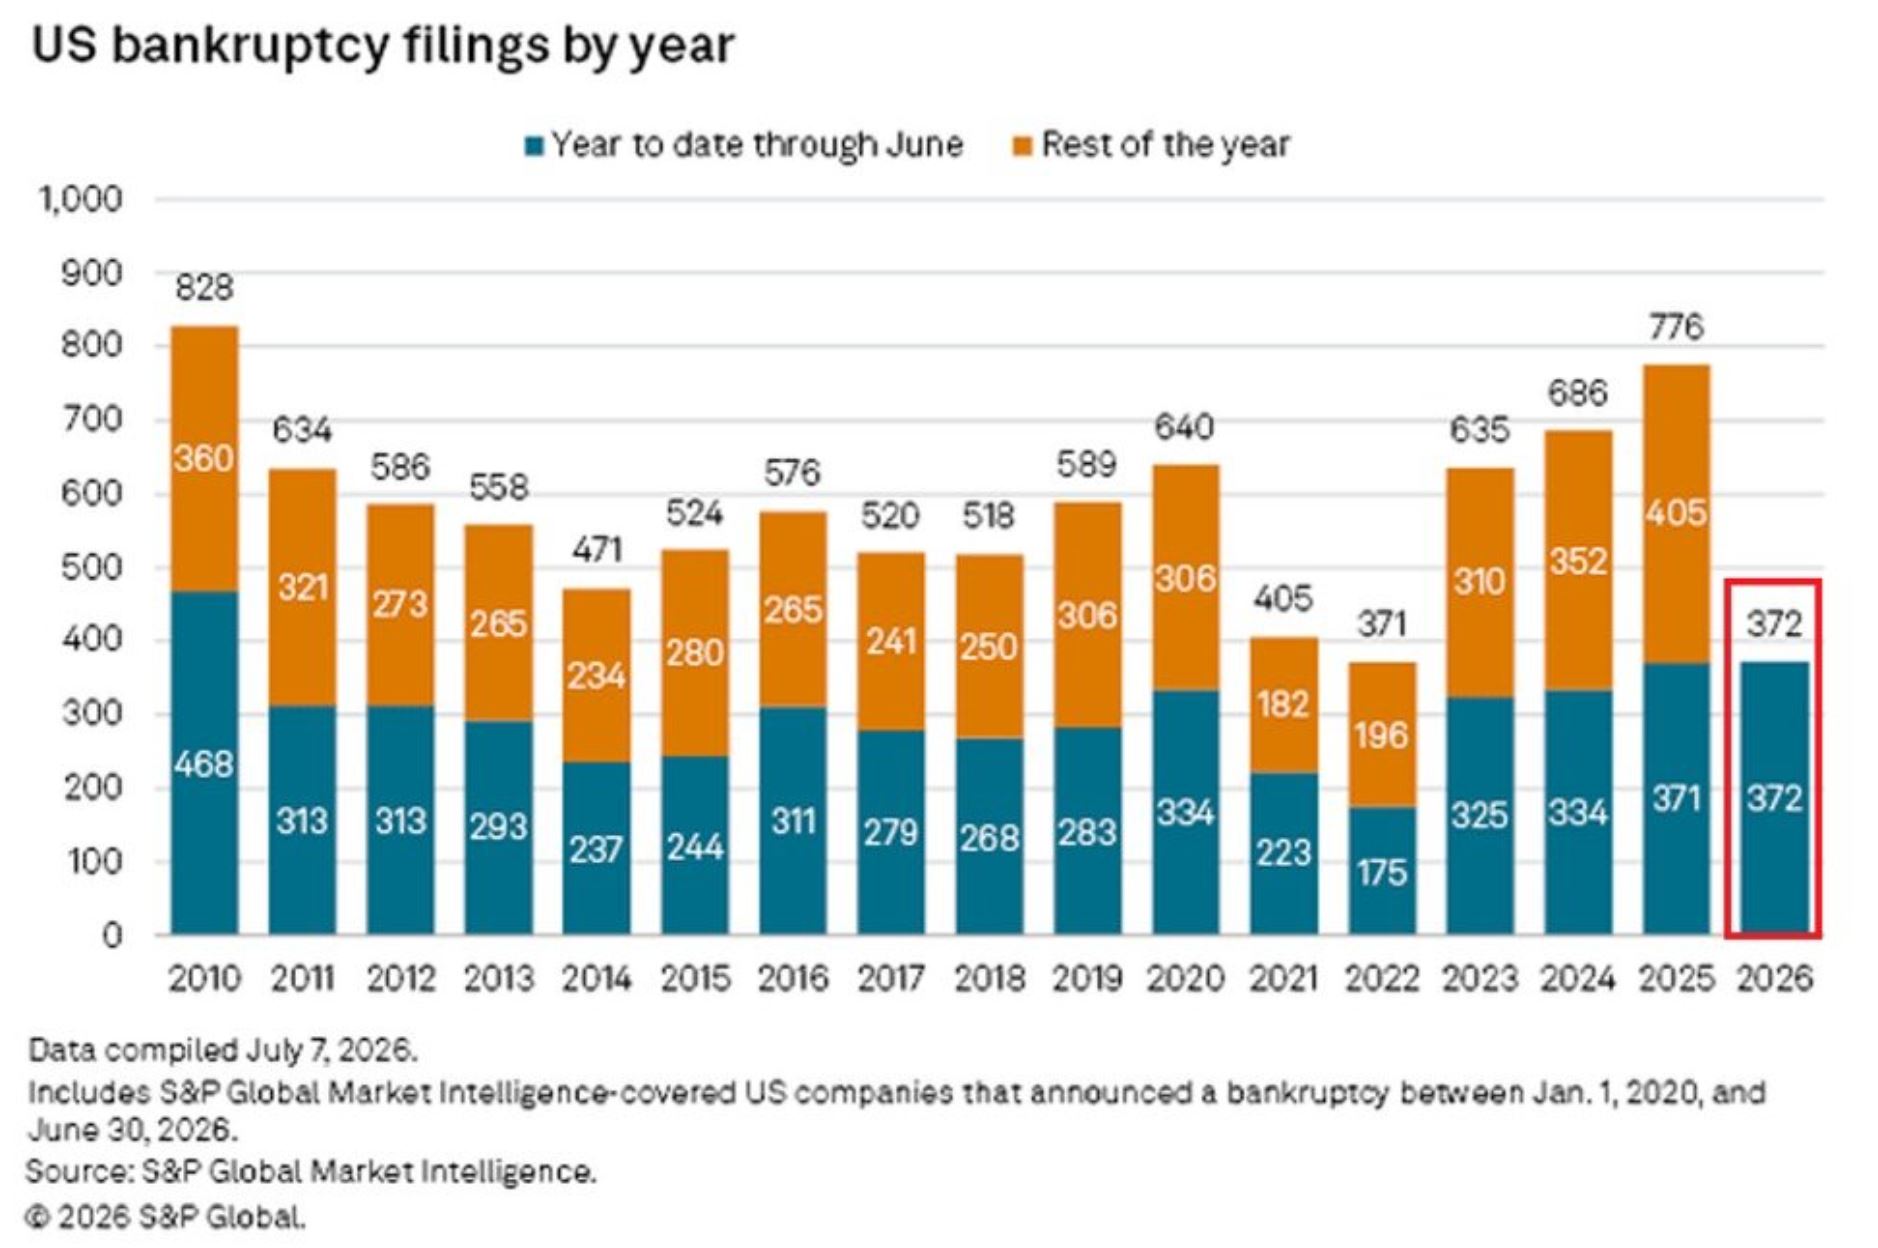
Key Changes in the Federal Bankruptcy EnvironmentFor a deeper dive into all the commentary and concerns responded to, we suggest watching the complete webinar. The most popular trend for 2026 is a continual boost in personal bankruptcy filings. While filings have not reached pre-COVID levels, month-over-month development recommends we're on track to exceed them quickly. Since September 30, 2025, personal bankruptcy filings increased by 10.6 percent compared to the previous fiscal year.
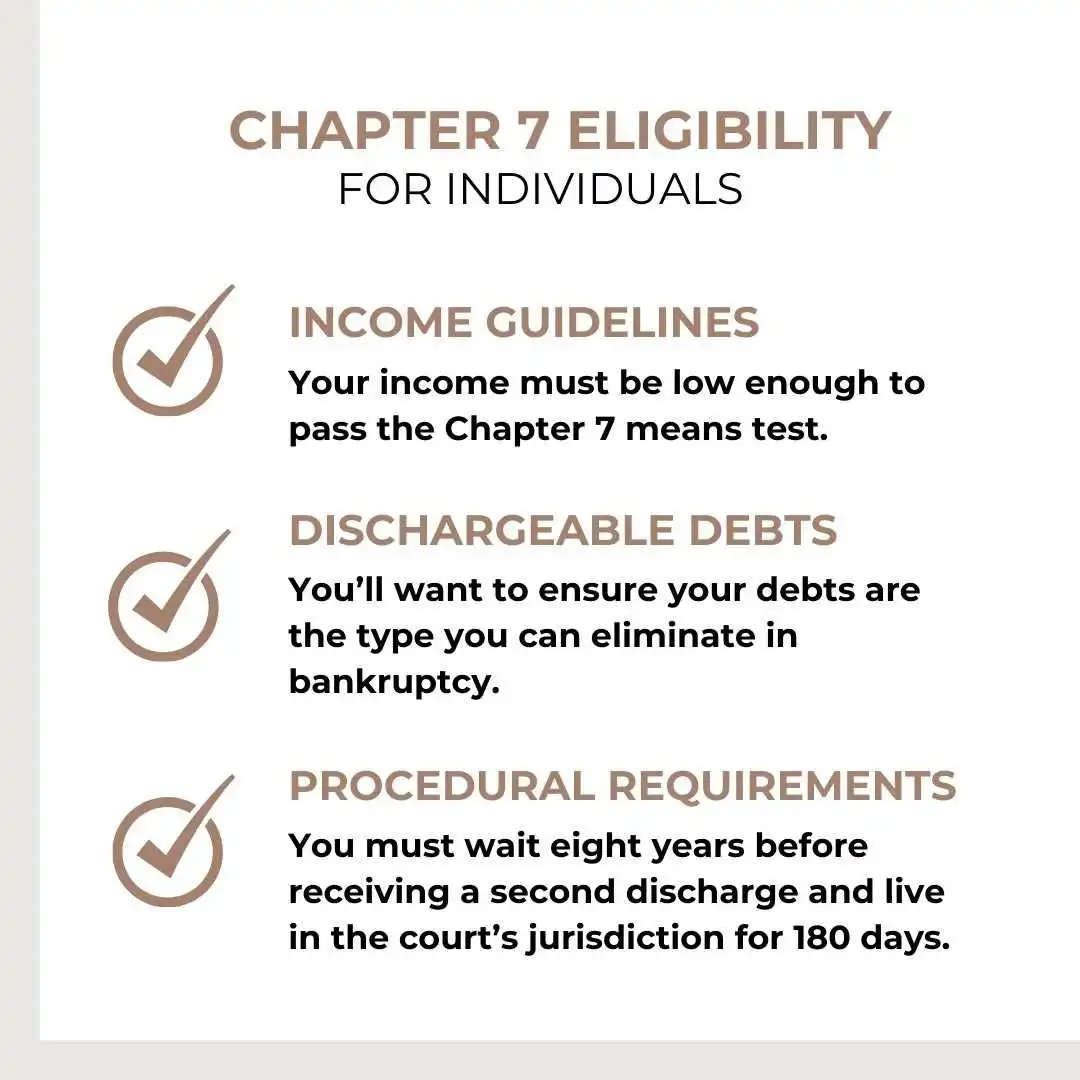
Evaluating Chapter 7 or 13 in 2026
While chapter 13 filings continue to increase, chapter 7 filings, the most common kind of consumer bankruptcy, are anticipated to control court dockets. This pattern is driven by consumers' absence of non reusable earnings and installing monetary strain. Other essential motorists include: Relentless inflation and elevated interest rates Record-high charge card financial obligation and diminished savings Resumption of federal student loan payments In spite of current rate cuts by the Federal Reserve, rate of interest stay high, and loaning costs continue to climb.
Indicators such as customers using "purchase now, pay later" for groceries and surrendering just recently bought cars show monetary tension. As a lender, you might see more repossessions and lorry surrenders in the coming months and year. You ought to likewise prepare for increased delinquency rates on automobile loans and home mortgages. It's also essential to closely monitor credit portfolios as debt levels stay high.
We predict that the real effect will hit in 2027, when these foreclosures relocate to completion and trigger insolvency filings. Increasing real estate tax and homeowners' insurance costs are currently pushing newbie lawbreakers into financial distress. How can financial institutions stay one action ahead of mortgage-related insolvency filings? Your group ought to complete a comprehensive evaluation of foreclosure processes, procedures and timelines.
Key Changes in the Federal Bankruptcy EnvironmentLots of upcoming defaults may develop from previously strong credit sectors. In recent years, credit reporting in personal bankruptcy cases has actually turned into one of the most controversial subjects. This year will be no various. However it is necessary that financial institutions persevere. If a debtor does not reaffirm a loan, you need to not continue reporting the account as active.
Here are a couple of more finest practices to follow: Stop reporting released debts as active accounts. Resume normal reporting just after a reaffirmation contract is signed and submitted.
Breakdown of Legal Fees
These cases often develop procedural problems for creditors. They can even miss out on key court hearings. Again, these issues include complexity to personal bankruptcy cases.
Some recent college graduates may juggle responsibilities and turn to bankruptcy to handle general debt. The takeaway: Lenders ought to prepare for more complex case management and think about proactive outreach to customers dealing with substantial financial stress. Finally, lien perfection remains a major compliance risk. The failure to perfect a lien within one month of loan origination can result in a creditor being dealt with as unsecured in bankruptcy.
Consider protective steps such as UCC filings when delays occur. The insolvency landscape in 2026 will continue to be formed by financial unpredictability, regulative analysis and developing consumer behavior.
By expecting the trends discussed above, you can reduce exposure and maintain functional durability in the year ahead. This blog site is not a solicitation for service, and it is not intended to make up legal guidance on particular matters, produce an attorney-client relationship or be lawfully binding in any method.

Latest Posts
Evaluating Chapter 7 and Chapter 13
Hiring the Best Bankruptcy Counsel for 2026 Claims
Rebuilding Personal Credit After Bankruptcy