All Categories
Featured

Potential Legal Impacts of 2026 Bankruptcy
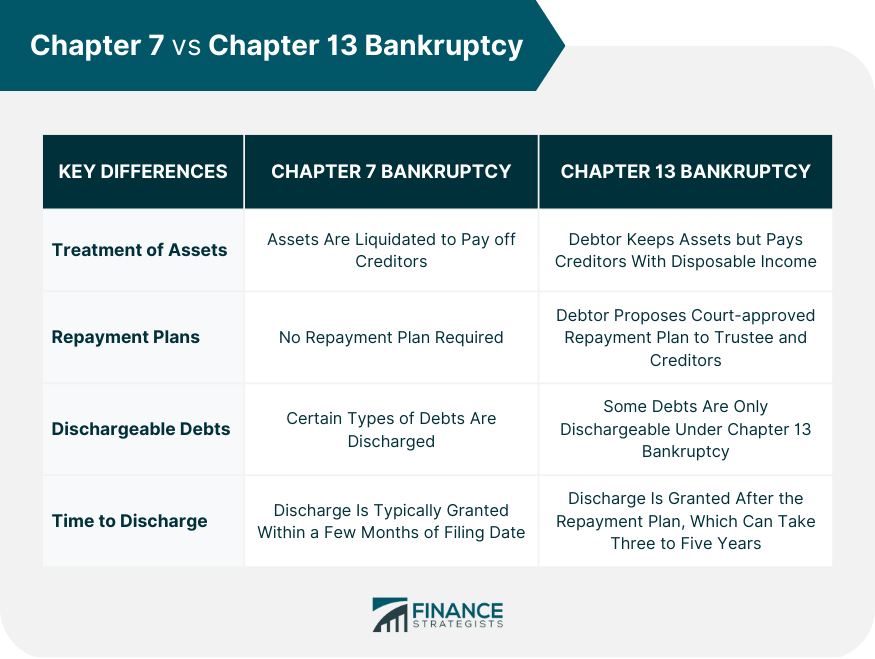
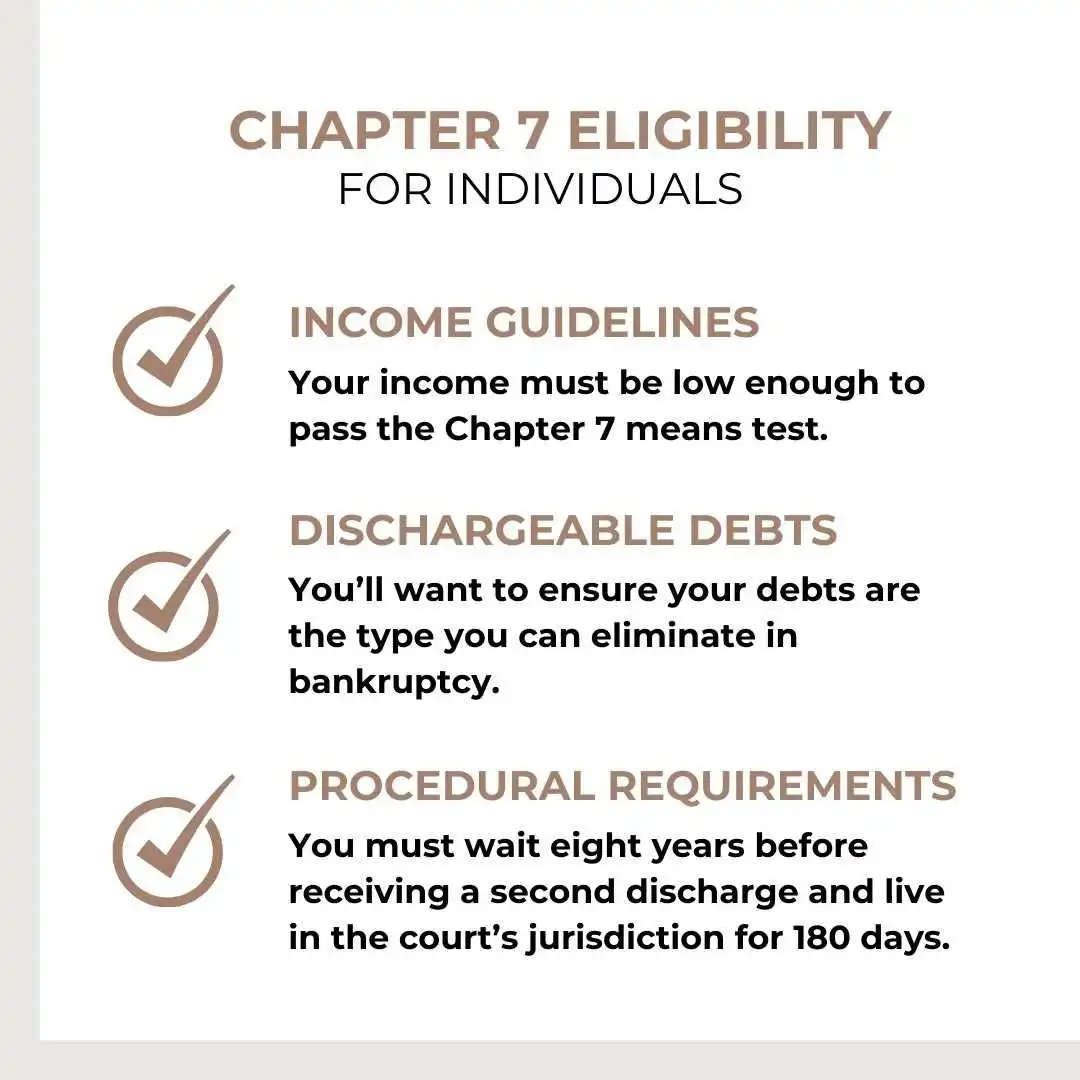
In Chapter 7, the trustee looks at your assets and compares their equity to the exemptions you declare. Equity is the value of the home minus what you owe on it. If your equity in a home, automobile, or other home is fully covered by exemptions, the trustee usually leaves that possession alone.
That analysis frequently figures out whether Chapter 7 is safe for somebody with built-up equity in Michigan property or a paid-off lorry. In Chapter 13, exemptions still matter, but in a various method. Instead of selling non-exempt residential or commercial property, the law generally needs that unsecured financial institutions receive a minimum of as much through your strategy as they would have received if you filed Chapter 7 and your non-exempt properties were offered.

A Michigan house owner with equity above the homestead exemption may pick Chapter 13, make a greater monthly payment for a set number of years, and still keep the house. Since the option between Michigan and federal exemptions can tilt the balance between Chapter 7 and 13, this is not something to think at.
If Chapter 7 looks risky but the client's income can support a reasonable Chapter 13 payment, the suggestion may move toward Chapter 13 to protect hard-earned property. How each chapter treats your particular financial obligations often matters more than any abstract pros and cons list. Unsecured debts, such as credit cards, medical expenses, payday advance, and many individual loans, generally get similar outcome in both chapters, however through different paths.
In Chapter 13, unsecured creditors typically receive a share of what you pay into the strategy, which might be anywhere from a little percentage to the full amount, and the staying balance can be released at the end if you complete your strategy. Secured financial obligations involve property that serves as security, such as a mortgage on a home or a lien on an automobile.
Finding the Right Legal Debt StrategyChoosing Chapter 13 Vs Chapter 7 in 2026
Keeping a protected asset frequently involves staying existing on payments and, in some cases, signing a reaffirmation contract that keeps you personally liable on that particular loan after personal bankruptcy. If you are far behind and can not catch up quickly, giving up the property in Chapter 7 erases your personal liability for any deficiency balance after the lender offers it.
You can spread out home mortgage or vehicle loan financial obligations over a three to five-year plan, which is called curing arrears, while also resuming your routine monthly payments. In some scenarios, Chapter 13 also allows a decrease of certain vehicle loan balances to the car's current value, an idea referred to as cramdown, though detailed guidelines use.
Priority and nondischargeable debts, such as current earnings taxes, kid support, alimony, and most trainee loans, stand in a different classification. These are generally not wiped out in Chapter 7, though the automated stay can stop briefly some collection while the case is pending. In Chapter 13, these financial obligations are typically paid completely through your plan before unsecured financial institutions get anything.
At Hensel Law Workplace, PLLC, a comprehensive financial institution list is mapped to these classifications so you see exactly which debts will be eliminated, which must be paid, and which chapter manages them more effectively. Understanding how long each chapter lasts and what every day life appears like during the case can decide feel less abstract.
Finding the Right Legal Debt StrategyShortly after filing, the automated stay usually stops garnishments, claims, and most collection calls. You attend a conference of creditors, typically called the 341 meeting, where the trustee asks concerns about your paperwork and financial resources. After that, you primarily await deadlines to pass and for the court to provide a discharge, unless the trustee requires more information or is exploring non-exempt assets.
Should You Use Chapter 7 in 2026?
You submit the case, and the automated stay enters into impact, stopping garnishments, foreclosure sales, and most collection activity. You propose a repayment strategy, start making monthly payments to the Chapter 13 trustee, and participate in a 341 conference and, in a lot of cases, a verification hearing where the judge considers whether to authorize the plan.
Many Michigan filers are amazed by how structured but manageable the everyday reality can be when the strategy is realistic. In Chapter 7, your main responsibilities are to be sincere, supply files, attend your meeting, and finish a needed financial education course. In Chapter 13, the included obligations include adhering to a budget, making every plan payment on time, and reporting considerable income modifications.
As soon as you comprehend how each chapter works, the next action is lining that up with your goals. One core tradeoff is speed versus structure. Chapter 7 moves much faster and typically includes no long-lasting payment obligations, which appeals to Michigan occupants and property owners who are existing on their home loans and have primarily unsecured financial obligations.

Latest Posts
Evaluating Chapter 7 and Chapter 13
Hiring the Best Bankruptcy Counsel for 2026 Claims
Rebuilding Personal Credit After Bankruptcy