All Categories
Featured


Pro Advice for Managing 2026 Bankruptcy Systems
Table of Contents
The task of the trustee is to see that your lenders are paid as much as possible. This person will completely evaluate your documentation, especially the assets you have in your ownership and the exemptions you want to claim, and can challenge any component of your case. Approximately a month after filing, the trustee will call a very first conference of lenders, which the debtor must participate in.
Creditors seldom attend a Chapter 7 insolvency conference; one or 2 lenders may attend a Chapter 13 conference, especially if there is a question as to the authenticity of some aspect of the strategy. Objections are generally resolved by settlement in between the debtor or the debtor's counsel and the lender.
The conference of financial institutions usually lasts about 5 minutes. You will receive notice of the place of the meeting but you might get in touch with the court to validate the address and time. (see California Insolvency Court Directory Site) The majority of Chapter 7 filings involve no non-exempt possessions, however, if you declared Chapter 7 and do have non-exempt possessions, you will have to turn over non-exempt residential or commercial property (or its fair market price in money) to the trustee after the conference.
If the residential or commercial property isn't worth an excellent offer or would be tough to offer, the trustee may decide to abandon the residential or commercial property (and return it to you). Trustees and creditors have 60 days to challenge the debtor's right to a discharge. If there are no challenges, you will get a notification from the court that your dischargeable debts have been released within three to six months.
Reviewing Legal Lawyer Fees for 2026
If your strategy is confirmed and you make great on it, the balance (if any) on the dischargeable debts you owe will be removed at the end of your term.
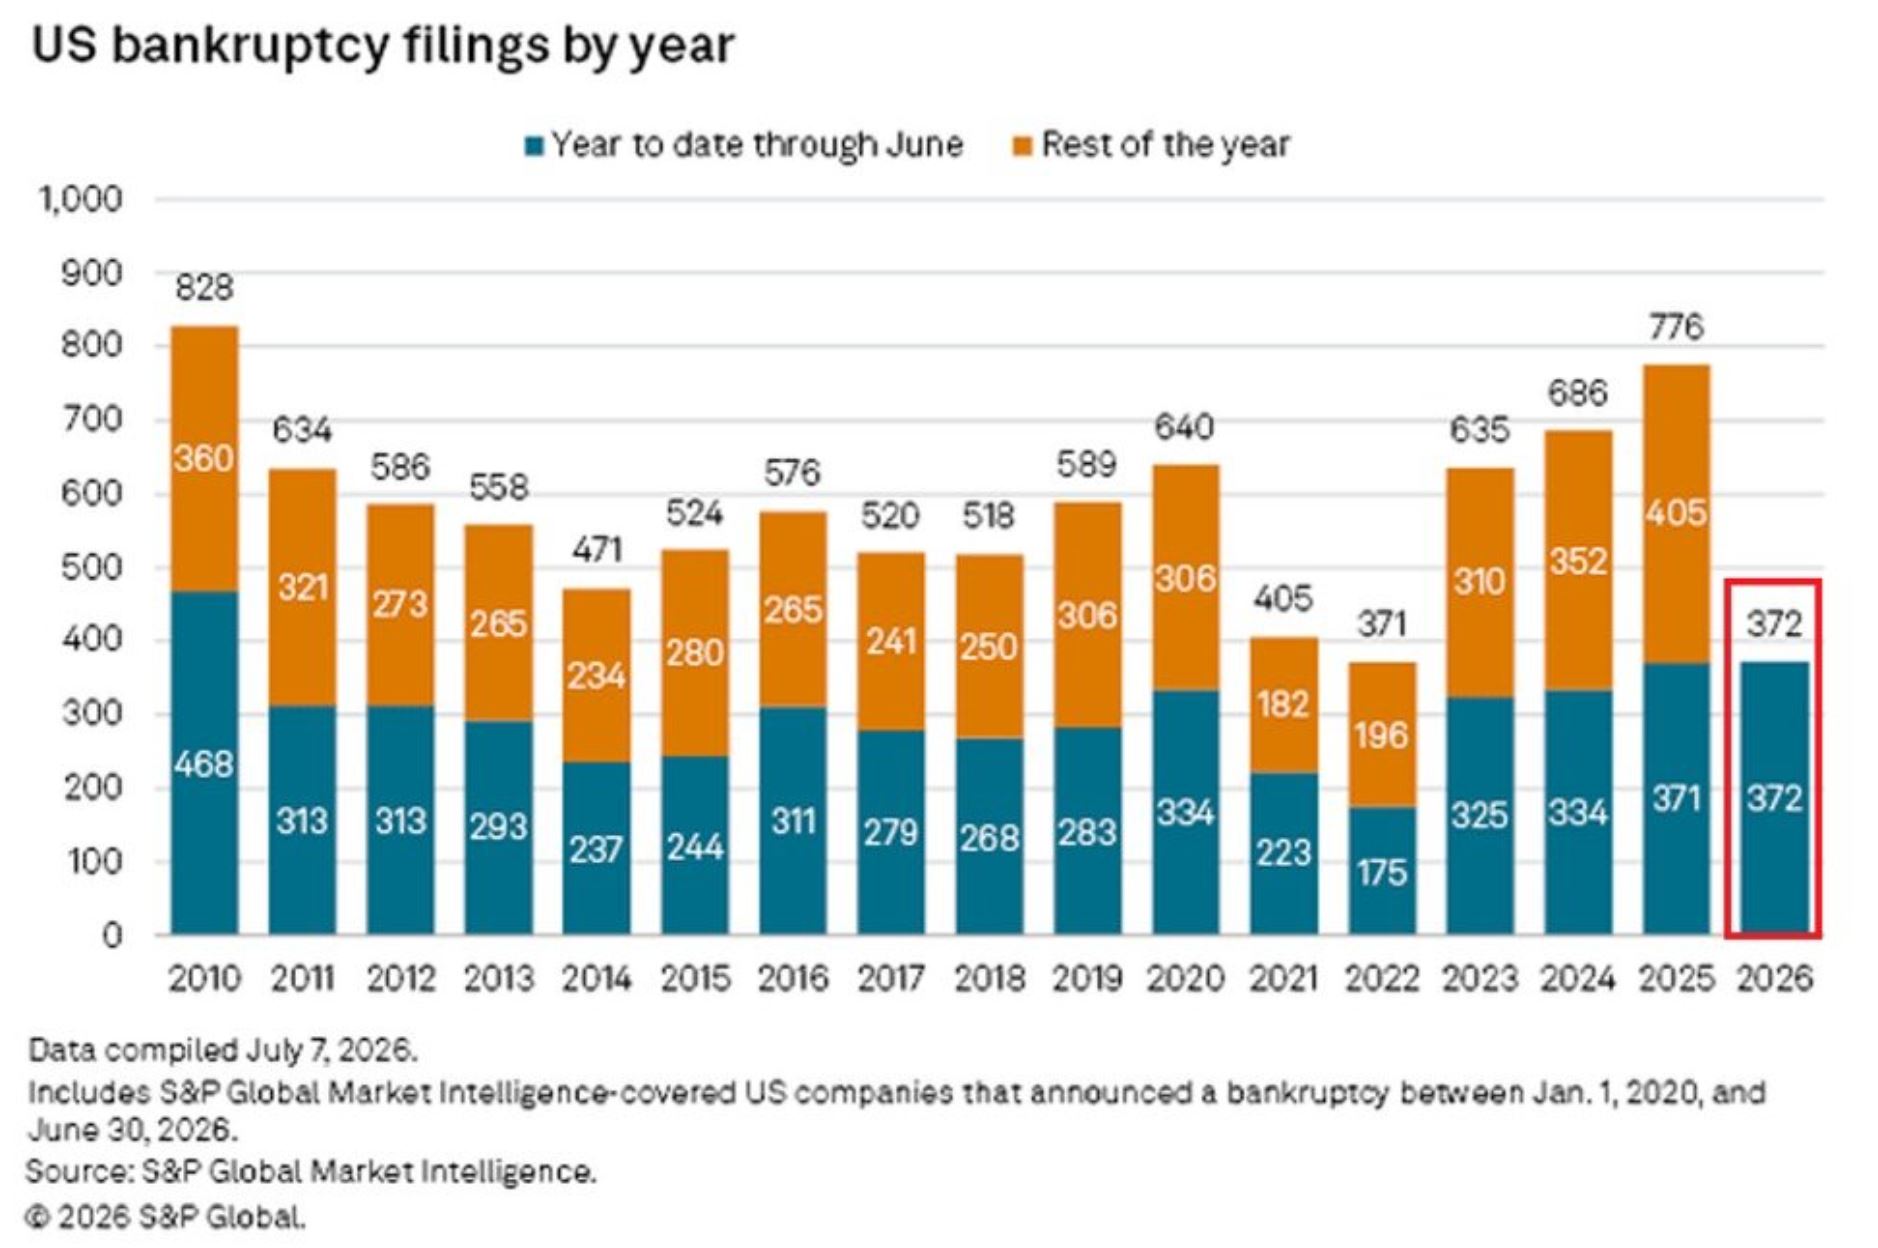
Organization personal bankruptcy filings, which started to rise in 2024 and 2025, are anticipated to continue to pattern upwards, a minimum of through the early part of this year. Company insolvency filings increased by nearly 5% for the 12 months ending June 30, 2025, from the very same period in 2024. Overall insolvency filings, consisting of personal, increased almost 12% in the very same time period.
Late 2025 rate of interest cuts and possible modifications to U.S. tariff policy may use some relief to having a hard time companies and enable them to address core issues and go back to health rather than declaring personal bankruptcy. The outlook for 2026 recommends that company insolvency risk will remain concentrated in sectors delicate to rates of interest, customer demand, and international trade dynamics.
Is Chapter 7 Right for 2026 Needs?
Brian DaviesManaging Partner, Capstone Partners Financial Advisory Provider Middle market companies, typically specified as organizations with $10 million to $1 billion in annual incomes, are facing a crossroads as 2026 methods. Amid relentless macroeconomic pressures, including rate of interest, tariffs, and maturity of pandemic-era financial obligation, lots of are grappling with liquidity constraints and tactical pivots.
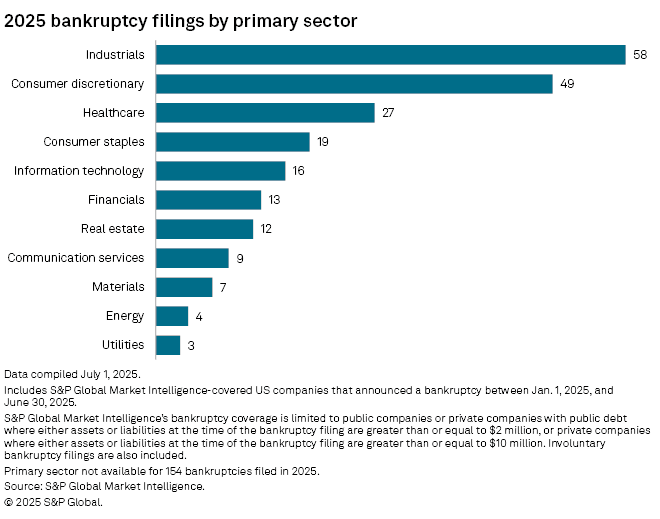
While volatility and a degree of unpredictability stand to be a hallmark of 2026, here are some company personal bankruptcy patterns that emerged in 2025 which can be expected to continue, at least through the early part of the year. After numerous years of decrease, bankruptcy filings in the United States continued to climb up in 2025, signifying installing monetary strain for families and businesses alike.
Courts. 1 Analysts point to a perfect storm of financial pressures that consist of persistent inflation and elevated rate of interest through the 3rd quarter as essential drivers behind this trend. While filings remain well below the historic highs seen after the Great Economic crisis, the uptick highlights growing vulnerability in consumer finances and mean broader obstacles for the economy in the months ahead.
Deciding Between Chapter 7 and 7 for 2026Using Bankruptcy to Stop Foreclosure in 2026
As stimulus funds ended and high interest rates, inflation, and rising financial obligation problems took hold, filings began to rebound. Between 2023 and the very first half of 2025, an 11%17% yearly increase in business personal bankruptcies ended up being the new regular. Industrial Chapter 11 filings increased nearly 20% year-over-year in both Q1 2024 and March 2025, with 2024 seeing a 20% rise over 2023.
$100 million in possessions) filing likewise increased 44% by mid-2025, and overall corporate personal bankruptcies struck a 14-year peak in 2024, with 694 filings. Considering That the Administrative Office of the U.S. Courts annual reporting is delivered on June 30 of each year, the main results for the 2nd half of 2025 will not be readily available till July 2026.
Two consecutive rates of interest cuts late in 2025, in addition to possible revisions to the U.S. tariff policy, may not be enough to reverse damage to having a hard time services, however it may offer some favorable relief for those that are hanging in the balance. 3, 4 While pockets of stability and development exist, the majority of major market groups within the U.S. The combination of shrinking discretionary earnings and competitive pricing characteristics makes this sector a prime candidate for restructuring, as highlighted in Capstone Partner's June 2025 Restaurants Sector Report. The FDIC has flagged industrial realty loaning as an essential risk for 20252026, citing loan maturities and refinancing challenges in an environment of higher yields.

Latest Posts
Evaluating Chapter 7 and Chapter 13
Hiring the Best Bankruptcy Counsel for 2026 Claims
Rebuilding Personal Credit After Bankruptcy