All Categories
Featured

Steps to Prepare for a 2026 Bankruptcy Filing
Table of Contents
California has four federal bankruptcy court districts: Bankruptcy isn't the ideal move for everybody. It can be a great alternative if: Your debt is so big you might never realistically pay it off The majority of your financial obligation is the kind that can in fact be cleaned out (more on that below) Lenders are suing you, garnishing your earnings, or threatening to take your home You've currently tried other choices and they have not worked It may be a great alternative if: The majority of your debt is the kind that can't be erased (like student loans or child assistance) You have possessions you do not wish to risk losing Your financial problems are short-lived for example, you just lost a task but expect earnings quickly You recently got a large quantity of credit or made large purchases Submitting for bankruptcy likewise impacts your credit.
Figure out if you can lower your costs, increase your income, negotiate lower rate of interest, or offer some property. You may be able to make modifications to your circumstance to begin settling your financial obligations by yourself. Lots of lenders would rather work out a payment plan than handle insolvency court.
You combine numerous debts into one loan preferably with a lower rate of interest. This doesn't lower what you owe, however it can make payments more workable. Nonprofit credit therapy firms can assist you set up a strategy to repay your debts, typically with decreased interest. Search for companies approved by the U.S
Steps for Filing for Bankruptcy During 2026You (or a business in your place) negotiate to pay less than the total owed. debt settlement companies often charge high costs (often upfront, whether or not they settle your debt), and settled financial obligation can count as taxable earnings. If you have extremely little income and almost no properties, financial institutions may not have the ability to collect from you anyway.
Steps to File Bankruptcy Efficiently in 2026
Insolvency does remove all debts. Some of the most common financial obligations that you can not get rid of in personal bankruptcy are: These endure insolvency.
Current income tax debts usually can not be wiped out. Some older tax debts might qualify, however the guidelines are complicated. Typically, wages, wages, and commissions you owe to employees are provided concern status in personal bankruptcy, which suggests they get paid before many other creditors.
Financial Impacts of Declaring Bankruptcy in 2026If you triggered injury or death while driving under the influence, that financial obligation usually makes it through. If a creditor can show you lied or committed fraud to get credit, that financial obligation likely won't be erased. Fines or charges owed to a government agency (like regulatory penalties, court fines, or penalties enforced as punishment) are usually not dischargeable in insolvency.
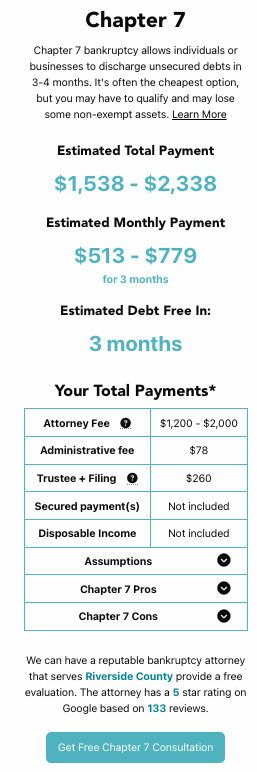
There are four common kinds of bankruptcy cases, called by the chapter of the federal Bankruptcy Code that explains them. It cleans out most unsecured financial obligations like credit cards and medical bills fairly rapidly, usually within 3 to 6 months.
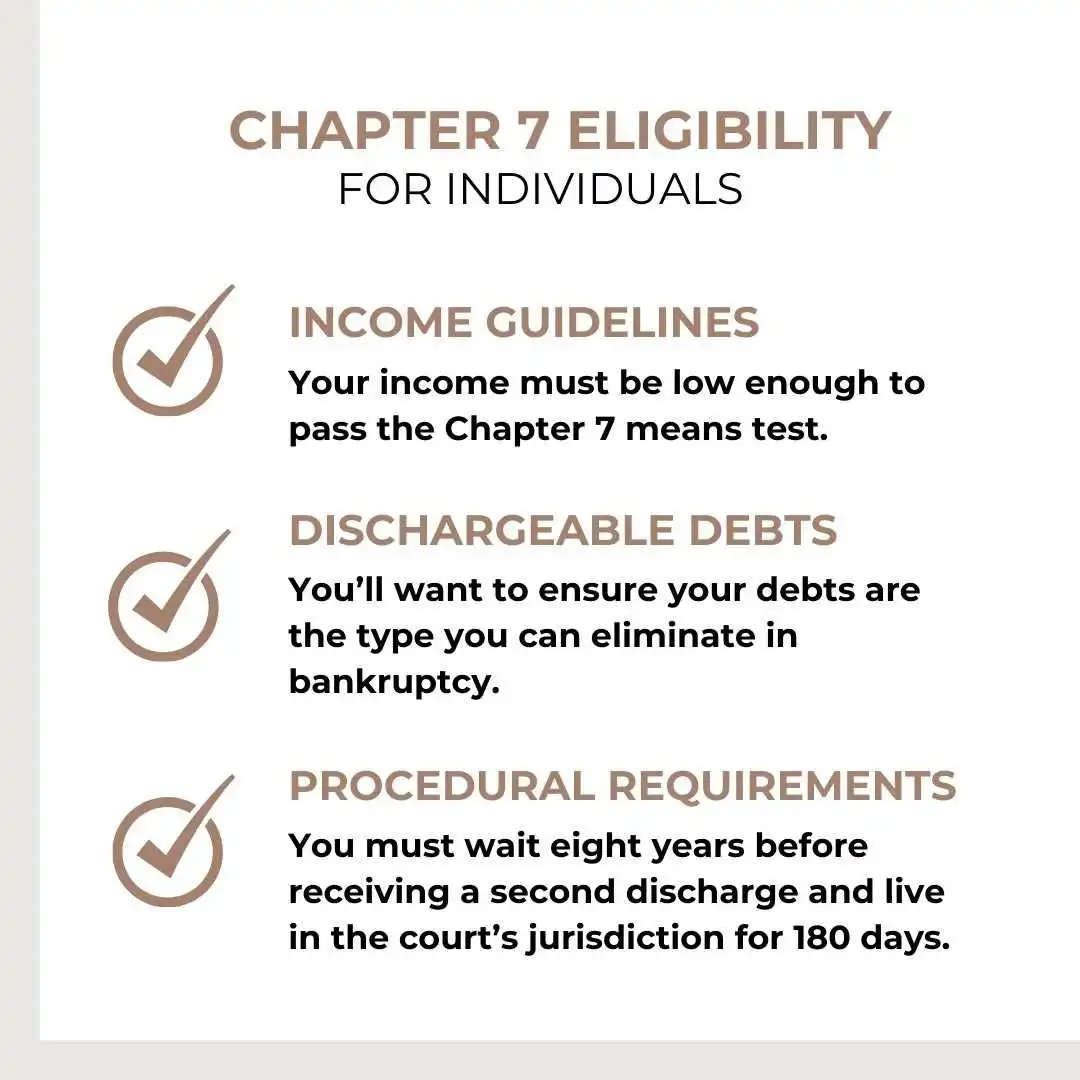
California has exemptions that protect particular home, like a part of your home equity, an automobile up to a certain worth, and basic home items. You should make less than a specific amount of money to qualify You need to have received credit therapy from an authorized credit counseling company in the last 6 months.
Comparing Chapter 7 and Chapter 13 Laws
It is a repayment strategy for people with regular income who have property, like a home they wish to conserve from foreclosure, or who do not quality for Chapter 7. It is likewise helpful if you have financial obligations that can't be discharged in Chapter 7 but can be managed gradually.
The debtor generally keeps their possessions and continues to run the business while dealing with a plan to settle the lenders. This type is a customized kind of personal bankruptcy specifically for household farmers and household fishermen with routine income. The debtor keeps their home and works out a payment plan with the creditors.
Deciding to submit for bankruptcy is a big decision. Considering that personal bankruptcy is a customized area of law that is extremely complicated, it is a good concept to get suggestions from a personal bankruptcy attorney.

Latest Posts
Evaluating Chapter 7 and Chapter 13
Hiring the Best Bankruptcy Counsel for 2026 Claims
Rebuilding Personal Credit After Bankruptcy